



Market close
The KSE-100 index closed at 177,382.57, up 610.38 points or 0.35% from the previous close of 176,772.19. Market breadth was mixed: the day's largest gainers included SELECT (price Rs22.86, +8.09%), TSPL (Rs20.04, +7.51%) and TREET (Rs28.69, +7.13%), while the biggest declines were in PASL (Rs10.64, -9.98%) and GEMMEL (Rs32.25, -8.51%). The watchlist comprised 47 stocks.
This week so far
Year-to-date weekly momentum has been modestly negative: the KSE-100 is down 491.31 points or -0.28% for the week so far. The index’s weekly range runs from a low of 176,294.33 to a high of 178,182.95, putting today's close closer to the top of the weekly band.
Sector performance this week was uneven. The strongest groups were Engineering & Steel (+4.98%), Fertilizer (+2.11%) and Pharmaceuticals (+0.59%). The weakest were Cable & Electrical (-3.77%), Technology (-1.85%) and Oil & Gas Marketing (-1.70%).
This month
Over the month the KSE-100 is up 10,973.32 points or 6.59%. The month's trading band sits between 166,409.25 (low) and 179,335.24 (high), so the index remains inside its monthly range after a significant monthly advance.
What moved the market
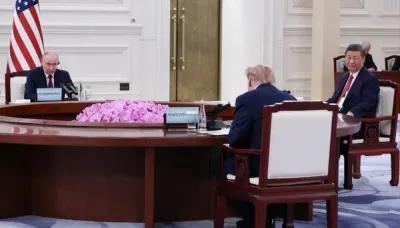
No single news item in TFD’s coverage clearly explained today's rise. There were several notable stories published today — including international coverage of the three-way summit in China (Trump greets Xi and Putin, says joint summit is 'making history') and Pakistan-focused items such as China vows to deepen cooperation with Pakistan, share governance experience — but none was presented in TFD’s feed as a direct market driver. In short, no single trigger was evident from the available headlines.
Rupee, gold and oil
Currency and commodity moves provided mixed signals. The US dollar was quoted at Rs276.46, up Rs0.04 (about 0.01%). Gold fell sharply: gold per 10 grams was Rs318,683, down Rs8,852 (-2.70%). Brent crude eased to USD 89.10 per barrel, down USD 2.88 (-3.13%), which may relieve some cost pressures for importing firms in oil-linked sectors.
Economy watch
Key policy and fuel-price references remain unchanged in today's feed. The State Bank of Pakistan policy rate stands at 12% (as of 28 October), according to the SBP. Official pump prices published for 28 October show petrol at Rs376.06 per litre and diesel (HSD) at Rs398.07 per litre.
What investors should watch
- Follow developments from international diplomacy and trade coverage, notably the three‑way summit reported in Trump greets Xi and Putin, says joint summit is 'making history', and any follow-up on China–Pakistan ties in China vows to deepen cooperation with Pakistan, share governance experience, which policymakers and investors may parse for trade or financing cues.
- Monitor commodity price movement after Brent's drop and gold's fall — both appear in today's data and influence sector cost profiles and safe-haven flows.
- Watch domestic policy markers: the SBP policy rate and official fuel prices cited for 28 October remain central reference points for interest-rate sensitive sectors.
- Keep an eye on individual stock momentum: outsized moves in names such as SELECT, TSPL, TREET and PASL may continue to affect market breadth in the near term.
This brief is market commentary for information only and is not investment advice. Figures as at the close of Friday, 20 November 2026.
